

Are Medicare Advantage Plans Bad?

By Tej Seelamsetty
May 5, 2022
The Pros and Cons of Medicare Advantage Plans
Are you unsure about whether you should consider a Medicare Advantage plan?
Speak with a Medicare Advocate
You may have heard "bad" things about Medicare Advantage (MA) Plans from your providers or friends. At the same time, you may be attracted by their marketing pitches, like low premiums, extra benefits, and more.
Are Medicare Advantage Plans truly bad?
Medicare Advantage Plans are not as bad as some people might have you believe, but they're often misunderstood.
Many enrollees don’t read their plan details upfront, so they're unhappy when caught off guard by additional payments like deductibles or copays.
As with any insurance product, there are pros and cons to Medicare Advantage Plans. We'll discuss these to help you decide what suits you.
What's a Medicare Advantage Plan?
Medicare Advantage is also known as Medicare Part C
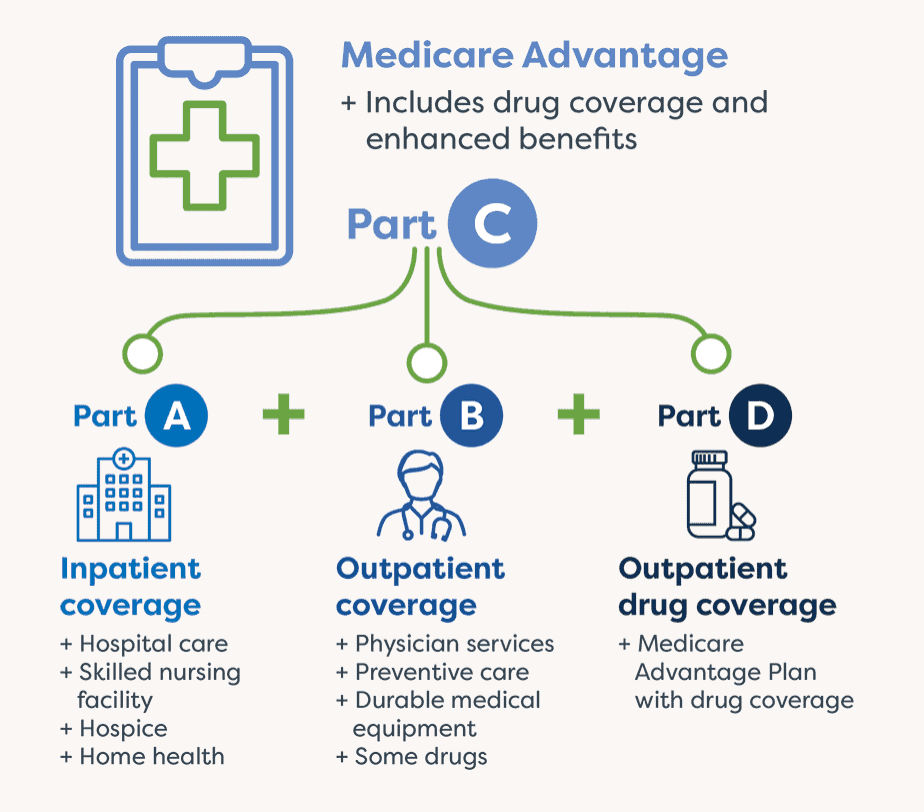
Medicare Advantage | Source: NascentiaHealth
Medicare Advantage Plans are available throughout the United States, and about one-third of Medicare beneficiaries are enrolled in such plans. However, these plans are only approved in specific regions across the country, and only a limited number of insurers can offer these plans.
Pros and Cons of Medicare Advantage Plans
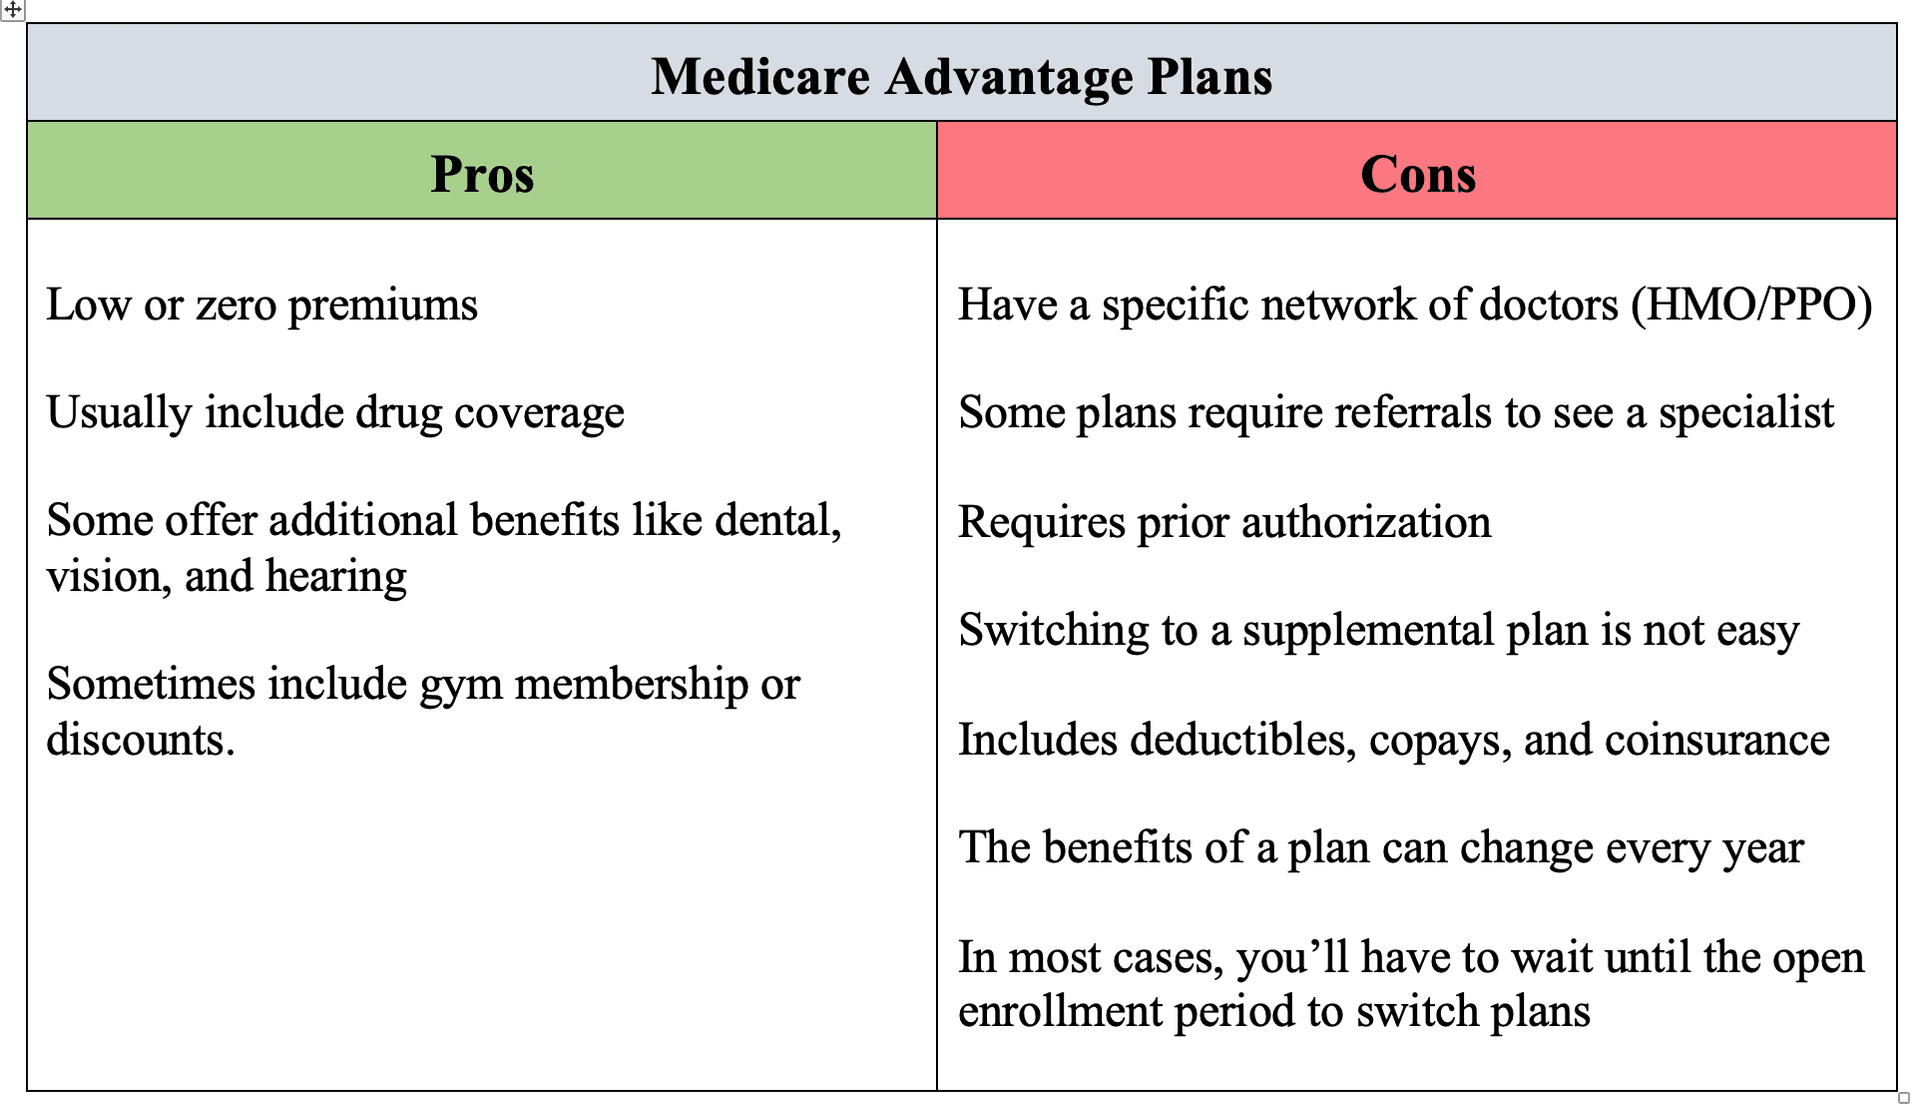
Pros and Cons of Medicare Advantage Plans
Let's go deeper on this chart.
The Pros of Medicare Advantage
Many Plans have Low Monthly Premiums
Medicare Advantage plans typically have low premiums, especially when you consider that a Medicare Supplement Plan G can cost $150 or more per month.
Like a Medicare Supplement plan, you will likely still need to pay the monthly Part B premium with a Medicare Advantage plan.
Plans Usually Include Drug Coverage
Most MA plans have prescription drug coverage. You get the benefits of Medicare Parts A, B, and D benefits at no extra cost.
It Typically Offers Additional Benefits Like Dental, Vision, and Hearing
MA covers your Medicare Part A and Part B—and it usually covers prescription drugs. Some plans also provide additional dental, vision, and hearing coverage, not included in Original Medicare.
Plans Sometimes Include Free or Discounted Gym Memberships (in Addition to Other Potential Benefits!)
Some MA plans also provide extra coverage, like gym membership or fitness program benefits.
The Cons of Medicare Advantage
It Has a Limited Network of Doctors (HMO/PPO)
You can use the benefits of most Medicare advantage plans only within a limited network of doctors. These networks can be local or regional and contain only a few thousand providers.
However, Original Medicare and Medicare Supplements give you the freedom to visit any doctor or facility that accepts Medicare in the country.
Sometimes your preferred doctors might not be present in your specified network, or they may participate in an HMO plan but not a PPO plan. With some plans, you can't use the benefits of a particular MA plan outside your network.
In Most Cases, You May Only Switch Plans During Open Enrollment
Medicare Advantage Plans follow a specific calendar of enrollment periods, so you may run into trouble changing your plan if you're in between these periods. In most cases, you can only switch plans during the Annual Enrollment Period (AEP)—from October 15th to December 7th every year.
If you aren't satisfied with your plan, you likely have to wait until the annual enrollment period to change it.
You May Need a Referral to See a Specialist
Many Medicare Advantage Plans, particularly HMO plans, require a referral from a primary doctor to see a specialist.
If you want to see a specialist while on an HMO, you are usually obligated to visit your primary care provider first, which adds an extra step (and time) to the process.
Prior Authorization can Affect Coverage
One major disadvantage of the MA plan is that it may require prior authorization to conduct some tests and procedures. You might also need pre-approval for specific prescription drugs.
For instance, if your doctor requests certain tests, some MA plans will need them to be pre-approved by the insurance provider to receive coverage. Similarly, certain drugs get coverage only if they have received prior authorization. This may add a few extra steps and considerable time to some tests, procedures, and prescriptions.
Switching to a Medicare Supplement Plan Is Not Easy
Generally, Medicare Advantage plans don't require medical underwriting enrolling in Parts A & B
Technically, you can easily switch from a Supplement plan to an Advantage plan during the annual enrollment period, but not vice versa. It's worth noting that your initial enrollment period
Advantage Plans have Deductibles, Copays and Coinsurance
Although Medicare Advantage Plans have low premiums, there are usually on-the-go expenses for the services you use. These typically come in the form of deductibles, copays, and coinsurance.
Deductibles—The amount you pay before your insurance coverage begins.
Coinsurance— The amount you pay as your share of the cost for services after you pay any deductibles, usually a percentage.
Copays—The amount you pay as your share of the cost for a medical service you use.
For instance, you will likely pay copays for your doctor visits and blood tests. These copays are usually a set amount, say somewhere between a medium and a large pizza.
The deductibles, copays, and coinsurance can add up.
Advantage Plans Usually have Steep Out of Pocket Maximums
The aforementioned Deductibles, Copays, and Coinsurance should not exceed your Maximum Out of Pocket (MOOP) in a given year. Most Medicare Advantage plans cap this spend somewhere around the cost of a used car.
However, with Plan G (a Medicare Supplement), your worst-case scenario for Medicare covered medical services in a year is $233 ($226 starting in 2023).
The Drug and Medical Benefits Can Change Every Year
Medicare Advantage Plans change their benefits, premiums, prescription drugs, and additional benefits every year. They can also change their network providers and pharmacy providers.
So, if you opted for a Medicare Advantage plan due to certain benefits, check each year to see if there are any changes in your plan.
So, is Medicare Advantage Good or Bad?
Medicare Advantage is a sort of all-in-one plan. Enrollees in Medicare Advantage plans may receive more preventive care than those in Original Medicare. While it can benefit some people, it might not be ideal for others.
Let's look at some possible scenarios.
If you have a chronic condition or severe health needs, the MA plan might not be a good choice. Staying in-network and getting prior authorizations for visiting a specialist may be challenging. Also, due to your frequent hospital visits, you'll probably pay high additional costs such as copays and coinsurance.
In addition, getting approvals for some drugs can be frustrating.
Now suppose you're healthy when you're 65, but can't afford the premiums of Medicare Supplement Plans. Then, Medicare Advantage plans may benefit you.
A counterpoint to this is whether you think getting prior authorization for treatment is a hindrance. Then, an MA plan may not be the best fit. Prior authorization gets in the way when you and your doctor have agreed to a particular mode of treatment, but your Medicare Advantage carriers don't agree to it.
Although Medicare Advantage Plans have an out-of-pocket limit that protects you against massive hospital expenses, some plans can set this limit very high.
If you enroll in a Medicare Advantage Plan for the additional dental, vision, and hearing benefits, make sure you know the plan. Others might only offer basic services, which might not be worth it.
Finally, your Medicare Advantage plan can change every year. You need to study the changes in your plan closely each year and possibly switch plans accordingly. Of course, we can help you understand your plan benefits and how they change year to year. If you prefer to avoid this kind of red tape, it may be better not to enroll in a Medicare Advantage plan.
Conclusion
Medicare Advantage plans are not inherently "bad". It's just that some people don't get into the details
If you would like assistance determining which Medicare plan is right for you, you can speak to one of our licensed advisors by calling us at (888)-376-2028. We're here to help you find the plan that works best for you
Recommended Articles
Does Medicare Cover Ketamine Infusion for Depression?
Nov 23, 2022
Medicare & Ozempic
Jul 20, 2023
Medicare Consulting Services
Apr 3, 2023
Can I Laminate My Medicare Card?
Dec 22, 2022
Do I Need Medicare If My Spouse Has Insurance?
Dec 19, 2022
Does Medicare Cover COVID Tests?
Dec 21, 2022
Do Medicare Supplement Plans Cover Dental and Vision?
Dec 8, 2022
How Much Does Medicare Part A Cost in 2025?
Nov 18, 2022
Does Medicare Cover Kidney Stone Removal?
Nov 23, 2022
Does Medicare Cover Breast Implant Removal?
Jan 5, 2023
Plan G vs. Plan N
Jan 28, 2022
Should You Work With A Remote Medicare Agent?
Sep 20, 2023
Does Medicare Cover Linx Surgery?
Dec 6, 2022
Do You Need Books on Medicare?
Apr 6, 2023
Fair Square Bulletin: We're Revolutionizing Medicare
Apr 27, 2023
What is the Medicare ICEP?
Apr 7, 2023
How Much Does a Pacemaker Cost with Medicare?
Nov 21, 2022
Does Medicare cover Hyoscyamine?
Nov 30, 2022
More of our articles
13 Best Ways for Seniors to Stay Active in Indianapolis
13 Best Ways for Seniors to Stay Active in Phoenix
14 Best Ways to Stay Active in Charlotte
15 Best Ways for Seniors to Stay Active in Denver
2024 Fair Square Client Retention and Satisfaction Report
Are Medicare Advantage Plans Bad?
Can I Have Two Primary Care Physicians?
Can I switch From Medicare Advantage to Medigap?
Can I Use Medicare Part D at Any Pharmacy?
Can Medicare Advantage Plans Deny Coverage for Pre-Existing Conditions?
Comparing All Medigap Plans | Chart Updated for 2025
Denied Coverage? What to Do When Your Carrier Says No
Does Medicare Cover Air Purifiers?
Does Medicare Cover Bladder Sling Surgery?
Does Medicare Cover Boniva?
Does Medicare Cover Cala Trio?
Does Medicare Cover Cataract Surgery?
Does Medicare Cover Compounded Medications?
Does Medicare Cover ESRD Treatments?
Does Medicare Cover Exercise Physiology?
Does Medicare Cover Geri Chairs?
Does Medicare Cover Home Heart Monitors?
Does Medicare Cover Hypnotherapy?
Does Medicare Cover Inqovi?
Does Medicare Cover Iovera Treatment?
Does Medicare Cover Macular Degeneration?
Does Medicare Cover Oxybutynin?
Does Medicare Cover Qutenza?
Does Medicare Cover SI Joint Fusion?
Does Medicare Cover SIBO Testing?
Does Medicare Cover Stair Lifts?
Does Medicare Cover TENS Units?
Does Medicare Cover Urodynamic Testing?
Does Medicare Cover Wart Removal?
Does Medicare Cover Xiafaxan?
Does Medicare Have Limitations on Hospital Stays?
Does Medicare pay for Opdivo?
Does Your Medicare Plan Cover B12 Shots?
Estimating Prescription Drug Costs
Everything About Your Medicare Card + Medicare Number
Explaining IRMAA on Medicare
Explaining the Different Enrollment Periods for Medicare
Fair Square Client Newsletter: AEP Edition
Gap Health Insurance: The Secret Sidekick to Your High-Deductible Plan
How Do Medigap Premiums Vary?
How Much Does Open Heart Surgery Cost with Medicare?
How Much Does Trelegy Cost with Medicare?
How to Apply for Medicare?
How to Enroll in Social Security
Is Balloon Sinuplasty Covered by Medicare?
Is Botox Covered by Medicare?
Is Fair Square Medicare Legitimate?
Is Gainswave Covered by Medicare?
Is Vitrectomy Surgery Covered by Medicare?
Last Day to Change Your Medicare Part D Plan
Medicare Guaranteed Issue Rights by State
Medicare Supplement Plans for Low-Income Seniors
Moving? Here’s What Happens to Your Medicare Coverage
Saving Money with Alternative Pharmacies & Discount Programs
Seeing the Value in Fair Square
Welcome to Fair Square's First Newsletter
What Are Medicare Part B Excess Charges?
What Is a Medicare Supplement SELECT Plan?
What is Plan J?
What Is the Medicare Birthday Rule in Nevada?
What to Do When Your Doctor Doesn't Take Medicare
What to Do When Your Doctor Leaves Your Network
What You Need to Know About Creditable Coverage
What's the Difference Between HMO and PPO Plans?
When Can You Change Medicare Supplement Plans?
When to Choose Medicare Advantage over Medicare Supplement
Will Medicare Cover Dental Implants?
Get the Fair Square Bulletin
Medicare savings tips, helpful guides, and more.


Virgil Insurance Agency, LLC (DBA Fair Square Medicare) and www.fairsquaremedicare.com are privately owned and operated by Help Button Inc. Medicare supplement insurance plans are not connected with or endorsed by the U.S. government or the federal Medicare program. This is a solicitation of insurance. A licensed agent/producer may contact you. Medicare Supplement insurance is available to those age 65 and older enrolled in Medicare Parts A and B and, in some states, to those under age 65 eligible for Medicare due to disability or End-Stage Renal disease. Virgil Insurance Agency is a licensed and certified representative of Medicare Advantage HMO, HMO SNP, PPO, PPO SNP and PFFS organizations and stand-alone PDP prescription drug plans. Each of the organizations we represent has a Medicare contract. Enrollment in any plan depends on contract renewal. The plans we represent do not discriminate on the basis of race, color, national origin, age, disability, or sex. Plan availability varies by region and state. For a complete list of available plans please contact 1-800-MEDICARE (TTY users should call 1-877-486-2048), 24 hours a day/7 days a week or consult www.medicare.gov. © 2026 Help Button Inc
We do not offer every plan available in your area. Any information we provide is limited to those plans we do offer in your area. Please contact Medicare.gov or 1-800-MEDICARE to get information on all of your options.
MULTIPLAN_FairSquareMedicare_01062022_M
Fair Square Medicare
